Lease advice: Don't let the deal negotiate you
Preparing a negotiation strategy ahead of time may help tenants secure key terms, avoid risk
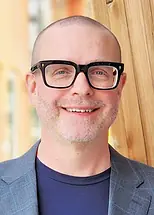
Shea Meehan is an attorney and the director of planning at Cornerstone Wealth Strategies, headquartered in Washington state and servicing clients nationwide.
| Melissa Dunn, Cornerstone Wealth StrategiesDespite businesses becoming increasingly virtual, many still need brick-and-mortar space. In most cases, that involves leasing. A lease is often among the most important commitments a business owner will make. Yet, many tenants focus on finding the right location or the lowest rent but pay little attention to negotiating terms beyond rent. That can be an expensive and long-lasting mistake.
Planning for the negotiation process before discussions begin is essential to securing favorable terms and managing risk. Otherwise, it's easy for a tenant to get swept up in the momentum of the transaction and sign a lease that doesn't protect their interests.
When negotiating a new lease or a renewal, know where your leverage lies. The landlord wants occupancy, brokers want commissions, and nobody gets paid until the deal closes. That creates a powerful incentive to get a deal done. This drive to complete the transaction is built into the lease negotiating process.
Once the tenant signs the lease, the tenant’s leverage disappears. A tenant must get everything they need and want — parking, signage approval, etc. — spelled out in writing before signing.
Too often, tenants rush into a lease thinking that the landlord will revisit terms after signing. They want the space now and the inertia of the deal whisks them along toward getting it done. Once the lease is executed, however, the landlord may have little reason to revisit unresolved issues. The result can be years of operating under a lease the tenant wishes they had negotiated more carefully.
Where future landlord approval is required for signage, improvements, or assignment, tenants should consider negotiating a provision preventing the landlord from unreasonably withholding, conditioning, or delaying consent.
For many small businesses, the landlord will require the owner's personal guaranty. A guaranty makes the owner personally liable for the tenant's obligations under the lease. If the business cannot pay, the landlord can pursue the guarantor personally. As a result, a poorly negotiated lease can jeopardize not only the business but also its owner.
One example that comes up too often relates to a building’s heating, ventilating, and air-conditioning system. A tenant signs a lease for a space, thinking it's a great deal. But they overlook the clause stating that they must maintain, repair, or, if needed, replace the HVAC equipment serving the space.
Two weeks into the lease, the old, worn-out AC unit dies. The bill to replace it is $25,000. The tenant is on the hook for the replacement cost. And they’ve likely personally guaranteed it.
This scenario happens quite often, yet it's entirely avoidable. A tenant might protect against full replacement costs by negotiating a compromise clause — for instance, reducing their financial responsibility by 5% for each year the equipment has been in service.
If the landlord wouldn't accept that term, at least the tenant could have obtained a professional inspection of the HVAC before signing the lease. Likely, a qualified professional could have told them that the AC unit would soon fail. Then, they could have considered finding alternate space.
Understanding operating costs beyond maintenance is also important. Is the lease triple-net, a gross lease, or something in between?
In a pure triple-net lease, the tenant pays operating costs in addition to rent. Operating costs typically include the expenses a landlord incurs operating a building, such as insurance, taxes, bookkeeping, roof repair, and snow removal. If there are multiple tenants leasing a building, leases usually prorate operating costs based on square footage. If there's a bad snow year, taxes go up, or other variable costs increase, the cost to the lessee will increase. A tenant can negotiate a cap to operating cost increases, but only if they understand it and know it's a negotiable term.
A gross lease means that the rent includes operating costs. Tenants who prefer cost predictability or new business owners may be better served by a gross lease. That way they know what they are paying and can budget accordingly.
Beyond operating costs and maintenance obligations, tenants may negotiate a wide range of lease terms, including the scope of any personal guaranty, assignment and subletting rights, renewal options, and rent escalation provisions. Whatever terms are negotiated, they should be clearly reflected in the signed lease.
Most importantly, tenants should remember that their leverage comes from the ability to walk away. Before signing, make sure the deal is one you can live with for the duration of the lease. Until then, your signature remains your strongest bargaining chip.
Shea Meehan is an attorney and the director of planning at Cornerstone Wealth Strategies, headquartered in Washington state serving clients nationwide.
Stay Informed. It’s Free.
Subscribe to our newsletters and get the latest news and insights delivered to your inbox.
We respect your privacy.
Unsubscribe anytime.
Thank you!
You’re subscribed. Keep an eye on your inbox for the latest updates.