Guest commentary...
The hidden risks of banking on a business sale
Creating a financial bridge helps protect your spouse
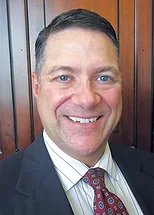
Todd Radwick, principal of Radwick Financial Group LLC, is an insurance and financial adviser. He can be reached at 509.679.4814 or [email protected].
| Radwick Financial Group LLCMany business owners spend decades building a company while setting aside too little for retirement. Their backup plan sounds reasonable: “Someday, I’ll sell the business and retire on the proceeds.” But as that “someday” approaches, the plan can collide with reality.
The market for the owner’s profession or industry may be weak. A niche business may require a buyer with rare expertise. Financial records may be disorganized, making it difficult to prove the company is healthy and worth the asking price. Even an excellent business can sit unsold for many years.
If you hope to sell within the next 10 years, one of the smartest moves is to develop a relationship with a capable business broker or a mergers-and-acquisitions professional well in advance. The right adviser does more than locate buyers and negotiate a reasonable price. They can help you identify weaknesses that reduce marketability, including unclear bookkeeping or inconsistent revenue.
It’s similar to preparing and staging a home for sale before prospective buyers arrive.
What if the business doesn't sell in time?
A long sales process creates more than financial uncertainty. It can become extremely stressful and emotionally exhausting, especially for a married couple who have spent one, two, or three years waiting for the right buyer. Now consider what happens if one spouse dies before the sale — particularly if that spouse was the only person who truly knew how to run the company.
Owners sometimes assume the survivor can simply sell the business, home, vehicles, boats, or other assets and downsize. In nearly 32 years as an adviser, I have seen how unreliable that assumption can be. Assets may not sell promptly; when they do, urgency can force fire-sale prices. A spouse already dealing with loss may also face debt, operating decisions, buyers, employees, and bills — all at once.
The question is not merely, “What is the business worth?” It is, “What financial position should my spouse be in if I am not here to complete the sale?”
A primary benefit of life insurance is its ability to deliver substantial, guaranteed, tax-free liquidity exactly when a family needs it most. The very event that causes the problem — death — is what triggers the solution right when it’s needed. That’s what life insurance does and what it’s intended to do. While life insurance cannot eliminate the grief of losing a loved one, having immediate liquid cash provides essential financial security and peace of mind during a difficult time.
Three currencies of life insurance
Obtaining life insurance requires three forms of currency:
- Money: Coverage has a premium. That is the visible cost.
- Health: Insurability can change without warning. Every day without adequate coverage is a day in which your “health currency” may decline. Today you may qualify; tomorrow, after a diagnosis or medical event, you may not.
- Love: Sometimes called the LQ, or Love Quotient. Insurance is ultimately an act of planning for someone else’s future. Money and health may make a policy possible, but love supplies the reason.
A short-term safety net for a short-term risk
For an owner planning to sell within 10 years, a 10-year term life policy may provide a practical bridge. The goal is not to buy a higher-priced permanent cash value policy, such as whole life, or universal life, or lock into a 20- or 30-year term policy. It's to create what I call an “instant guaranteed buyer.” Should the owner pass away before the deal closes, the policy's death benefit delivers the immediate liquidity the business sale was meant to provide. Also, because a shorter 10-year term is cost-efficient, this allows your premium to secure a larger, more meaningful death benefit to properly support your spouse.
For many owners, that safety net should be designed to accomplish two priorities. First, eliminate personal and commercial debt so the survivor has a clean slate. Second, provide enough remaining capital to support a dependable lifetime income strategy. For this, I often recommend a guaranteed lifetime income annuity, similar to a pension, that provides a reliable life income regardless of how long the surviving spouse lives or what the economy is doing. Everyone’s situation is unique, so the plan should be built and customized with your specific needs in mind.
If the business sells in the next few years and the protection is no longer needed, the owner can simply cancel the policy. If some coverage is still desired, a conversion option may allow all or part of the term policy to become permanent coverage without needing to prove any new medical insurability.
The cost of action and inaction
Every financial decision carries two costs: the price of action and the toll of inaction. A business owner pays for action through manageable premiums today. A surviving spouse pays for inaction far more dearly tomorrow. In wealth protection, good intentions mean nothing without execution.
A future business sale can be part of a retirement plan, but it shouldn't be the family’s only plan. Ideally, business owners would have other investments and retirement plans as well. But if a large portion of your retirement will come from the sale of your business, make sure your company is sale-ready and work with a knowledgeable professional who specializes in life insurance and annuities to design a temporary safety net while you get organized and ready to sell.
Todd Radwick, principal of Radwick Financial Group LLC, is an insurance and financial adviser. He can be reached at 509.679.4814 or [email protected].
Stay Informed. It’s Free.
Subscribe to our newsletters and get the latest news and insights delivered to your inbox.
We respect your privacy.
Unsubscribe anytime.
Thank you!
You’re subscribed. Keep an eye on your inbox for the latest updates.