RiverBank leads Spokane County in SBA lending
Commercial loans, deposit growth drive net income
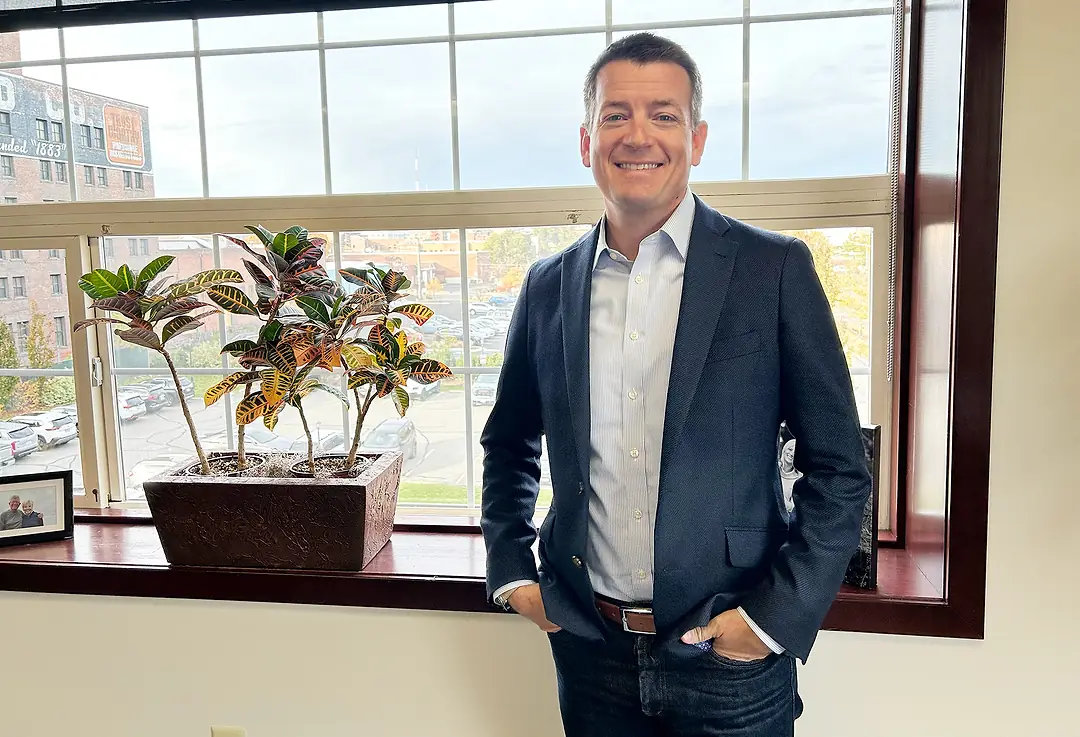
RiverBank CEO Mike Wilson says the bank is growing through its focus on relationship-based banking and technology.
| Karina EliasTwo years after developing its Small Business Administration lending department, RiverBank Holding Co., the parent company of Spokane-based RiverBank, has become Spokane County’s top SBA lender.
The increase in SBA lending comes as the community bank establishes a director of fintech position, reinforcing its founding principles of relationship banking and technology, says RiverBank CEO Mike Wilson.
From Oct. 1, 2025, through the end of June 2026, RiverBank originated 36 SBA loans totaling $9.7 million, over four times the volume of the county’s next top lender, according to data from the U.S. Small Business Administration's Seattle District. In fiscal year 2025, which ended Sept. 30, 2025, the community bank was also the top SBA lender in the county, originating 26 loans totaling $16.2 million, according to the Journal’s Top 20 Inland Northwest SBA Lenders list.
To foster growth, RiverBank recruited employees with specialized SBA lending expertise, including for two underwriting roles and two commercial loan roles, and promoted an internal employee into a business development role focused on acquiring SBA borrowers, Wilson says. As a Preferred Lender Program institution, RiverBank can approve eligible SBA loans internally.
SBA lending represents an expansion of RiverBank’s commercial banking services, which strengthens its ability to finance small businesses, Wilson says.
“For a long time, we did not really embrace SBA lending to the degree that we needed to,” Wilson says. “As a local community bank, to have that as a really strong product offering makes a lot of sense.”
The bank's new director of fintech is expected to begin their role in the coming weeks and will manage and expand RiverBank’s existing partnerships while identifying new opportunities, Wilson says.
“We would like to see it create a foundation for which we can continue to grow that area of the bank,” Wilson says. “It’s something that we’ve known would be an important part of the future.”
RiverBank has one office, located at 202 E. Spokane Falls Blvd. in Spokane’s University District, and employs 43 full-time employees. Since its founding in 2006, RiverBank has operated on a branchless, digital-first model, focusing on business banking and strategic technology-based investments and partnerships to spur growth.
In July 2025, RiverBank marked its first formal partnership with a fintech company through its collaboration with cannabis compliance company Green Check Verified Inc. The strategic partnership was years in the making, Wilson told the Journal, and aimed at growing the bank’s deposits, lending power, and national footprint while maintaining RiverBank’s branchless business model.
In its first few months of the partnership, RiverBank opened nearly 200 new accounts for cannabis-related businesses across the country. Since then, the number of accounts has remained at the same level, with a slight increase in deposits, Wilson says.
The partnership between Green Check and RiverBank is similar to that of the mobile payment platform Venmo, the Journal previously reported.
Green Check’s software integrates with point-of-sale and seed-to-sale systems throughout the cannabis supply chain to ensure that each transaction complies with state-, county-, and city-specific regulations. RiverBank, in turn, provides the actual banking services. The financial institution creates a new account for each cannabis business where it can hold funds and process transactions.
Although cannabis remains illegal at the federal level, it is legal for medicinal or recreational purposes in 41 states and the District of Columbia. In Washington state, the recreational use of cannabis became legal in 2012.
Leveraging specialized compliance technology to serve this emerging market has allowed RiverBank to capture a high-growth niche. The bank's focus on commercial lending and technology has increased its net income and deposits.
Riverbank reported net income of $1.3 million for the third quarter ending Sept. 30, up from $1.2 million in the year-earlier quarter, according to the bank's third-quarter financial results. Total deposits for Q3 2026 totaled $288.8 million, representing a 16.5% increase from $247.8 million in September 2025.
"Third quarter results reflect continued growth in revenue and total assets, funded primarily by core deposits," Wilson says in a press release. "Our targeted investments in personnel and technology are strengthening our foundation for continued performance in the fourth quarter."
In September, Wilson began a one-year term as chair of Community Bankers of Washington, an organization that advocates for community banks and provides educational resources to its members.
Wilson, who has served on the organization’s board for four years, says the role of Community Bankers of Washington has become increasingly important as mergers and acquisitions have reduced the number of banks headquartered in the state. According to the Puget Sound Business Journal, the number of banks headquartered in Washington state in 2008 totaled 97. As of July, the total had fallen to 31.
For several years, Washington state experienced a trend of bank acquisitions by credit unions, Wilson says. In 2024, about 32% of all bank acquisitions by credit unions nationwide happened in Washington state, the Journal previously reported.
The trend has slowed considerably since the state repealed a tax exemption for credit unions, he says. Effective Jan. 1, 2026, Washington state-based credit unions must pay a 1.2% business and occupation tax on gross income when they acquire or merge with a bank.
“The acquisition of community banks by state-chartered credit unions has slowed since, but it’s still very much an issue,” Wilson says. “There are fewer banks headquartered in the state; it’s just that much more important for us to have an organization where the banks are talking to each other about what’s going on.”
Across the country, community banks provide an estimated 60% of small business loans, making the institutions an important asset to local economies, Wilson says.
At RiverBank, continued investing in SBA lending, financial technology, and relationships with local businesses remain central to its growth, he says.
“It’s really our ability to meet the needs of this business community that has produced that growth,” Wilson says.

Stay Informed. It’s Free.
Subscribe to our newsletters and get the latest news and insights delivered to your inbox.
We respect your privacy.
Unsubscribe anytime.
Thank you!
You’re subscribed. Keep an eye on your inbox for the latest updates.